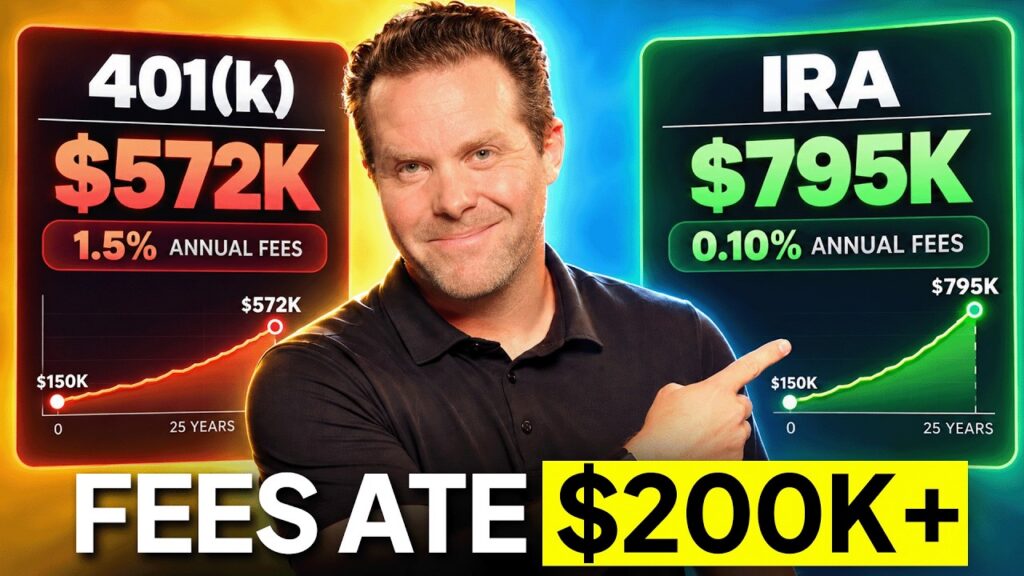
You left the job, but the 401(k) stayed behind. It’s still sitting in the funds you picked in a hurry during your first week, paying fees to a provider you didn’t choose, with a short menu of investments. For most people, the cost of leaving it there is bigger than they think.
Take a $150,000 old 401(k) at age 40. Left in a plan charging 1.5% a year, it could grow to about $572,000 by 65. Rolled to an IRA and invested in index funds costing 0.10%, the same money could grow to about $795,000. That’s a gap of more than $223,000, without adding a single dollar, at a hypothetical 7% return.
Mat Sorensen, CEO of Directed IRA and tax attorney, says the decision comes down to two things: what you’re paying in fees, and what you’re allowed to invest in. He walks through both in the video below, along with the rollover steps and the one mistake that turns a tax-free move into a taxable one.
Your Three Options
When you leave an employer, you can leave your 401(k) where it is, roll it into your new employer’s 401(k), or roll it into an IRA. The same choices apply to a 403(b).
- Fees are often higher
- You’re stuck with the plan’s fund menu
- Can make sense if you retire between 55 and 59½
- Keeps everything in one place
- Same plan-level fees and limited menu
- Usually lower costs
- Any stock or fund, or self-directed assets
- No tax with a direct rollover
Cashing out is technically a fourth option, but it’s taxable, and before 59½ it usually adds a 10% penalty.
Leaving the money in the old plan is the default most people end up with, and usually the most expensive. You’re no longer an employee, so you’re not getting a match, and you’re still paying the plan’s fees and living with its fund menu.
Rolling into your new employer’s plan keeps things simple, with one account for old and new contributions. But you trade one 401(k)’s fees and fund menu for another’s.
Rolling to an IRA is the right answer for most people. You can choose low-cost index funds, individual stocks, or any fund you like at a brokerage. With a self-directed IRA, the account can also own real estate, private funds, private lending, startups, and crypto.
What You’re Paying in Fees
401(k) fees are hard to see. There’s no bill. Investment fees, administrative fees, record-keeping and custodial fees, and revenue sharing built into the funds come straight out of your balance. Mat puts the all-in cost of a typical small-business 401(k) at around 1.5% a year, and sometimes 2%. On a $100,000 account, 1.5% is $1,500 a year.
Many people don’t realize they’re paying anything. A 2021 Government Accountability Office report found that 41% of 401(k) participants believed they paid no plan fees, and about 40% found the fee information hard to understand and use.
Here’s what those costs do over time:
Hypothetical illustration: a constant 7% annual return before fees that isn’t guaranteed, no new contributions, and fees taken as a percentage of the balance each year. Real returns and fees vary.
At 0.50% a year, the account reaches about $724,000. At 1%, about $644,000. At 1.5%, about $572,000. The difference compounds every year the money sits in a high-cost plan.
IRA costs are simpler. At a brokerage, you typically pay the expense ratio of the funds you pick, and you can pick low-cost ones. A self-directed IRA usually charges a flat annual fee instead of a percentage, so the cost shrinks as the account grows:
| Account size | $495 flat annual fee | 1.5% a year |
|---|---|---|
| $150,000 | $495 (0.33%) | $2,250 |
| $500,000 | $495 (0.10%) | $7,500 |
Directed IRA’s $495 annual account fee includes up to three assets. A fourth asset and beyond add $100 each, and transactions have their own fees. See the fee schedule.
What You Can Invest In
A 401(k) gives you a menu of mutual funds and target-date funds chosen by your employer or its advisor. Those funds often carry higher costs that help pay for the plan.
Use your 401(k) while you work there, especially if your employer matches contributions. Once you leave, the match stops, and the menu is still limited. In an IRA, you choose: low-cost index funds, individual stocks, or, with a self-directed IRA, the rental property down the street, a private fund, a startup, or crypto. Self-directing isn’t for everyone, but it’s only available once the money is in an IRA.
The Exception: Retiring Between 55 and 59½
There’s one case where leaving the money in the old 401(k) can be the better move. Under the rule of 55, if you leave your job in or after the year you turn 55, you can take withdrawals from that employer’s plan without the 10% early withdrawal penalty. Income tax still applies.
That exception belongs to the 401(k), not to an IRA. Roll the money to an IRA at 57, and withdrawals before 59½ generally face the 10% penalty again. If you plan to retire early and live on that 401(k) before 59½, keep it in the old plan, at least until you reach 59½.
Direct Rollover vs. 60-Day Rollover
The most expensive mistake is choosing the wrong kind of rollover.
- Money goes straight to the new IRA
- Nothing withheld
- No tax and no penalty
- 1099-R coded G (or H for Roth money)
- The plan sends you a check
- 20% withheld: $30,000
- You must redeposit the full $150,000 within 60 days
- Any shortfall is taxed, plus 10% if you’re under 59½
With a 60-day rollover, the plan writes the check to you and must withhold 20%. On $150,000, that’s $30,000 sent to the IRS. To avoid tax, you have to deposit the full $150,000 into an IRA within 60 days, which means coming up with the missing $30,000 from other savings. Whatever you don’t redeposit is taxed as income, and if you’re under 59½, it usually carries a 10% penalty too.
A direct rollover avoids all of that. The money goes from the 401(k) to the IRA, with nothing withheld and nothing taxed.
How to Roll It Over, Step by Step
A traditional IRA for pre-tax money, a Roth IRA for Roth 401(k) money, or both.
Ask for a direct rollover, not a distribution or a 60-day rollover.
Some plans mail a check made out to your IRA custodian for you to forward.
Codes G or H tell the IRS it was a rollover, so no tax is due.
A few details help the process go smoothly:
- Match the account types. Pre-tax 401(k) money goes to a traditional IRA, and Roth 401(k) money goes to a Roth IRA. If your old plan has both, open both. A Roth IRA has its own five-year clock, and years in a Roth 401(k) don’t count toward it, so opening a Roth IRA early helps.
- Use the plan’s form. Most 401(k) providers still use paper forms. Ask for a direct rollover. Some send the funds straight to the IRA custodian. Others mail you a check made out to the custodian for your IRA, which you forward.
- Roll over the whole balance. There’s no limit on a direct rollover. If you’re past 59½ and want some cash, roll everything first and take the withdrawal from the IRA.
- Expect a 1099-R. The old plan will send one, and it goes on your tax return. Code G (or H for Roth money) tells the IRS it was a direct rollover, so it adds no taxable income.
- A note for high earners. If you make backdoor Roth IRA contributions, pre-tax money sitting in a traditional IRA can make those conversions partly taxable under the pro-rata rule. Talk with your tax advisor before rolling pre-tax money into a traditional IRA. Rolling it into your new employer’s plan can avoid the problem.
If you’re still working and want to move 401(k) money now, see how in-service rollovers work.
The Bottom Line
An old 401(k) comes down to two questions: what are you paying, and what can you invest in? For most people, a direct rollover to an IRA lowers costs, opens up investment choices, and costs nothing in tax. The paperwork takes about an hour. Doing nothing has a price, and it grows every year.
If you want to self-direct, Directed IRA charges a flat annual fee and helps with the rollover paperwork from your old plan. Open an account online or book a free 15-minute call.

What to know before you move a 401(k) or IRA into a self-directed IRA, including the forms, timing, and mistakes to avoid.
Download the Free GuideOr book a free 15-minute callDirected IRA is a Tradename of Directed Trust Company. Directed Trust Company performs the duties of a directed custodian, and as such does not provide due diligence to third parties on prospective investments, platforms, sponsors or service providers and does not sell investments or provide investment, legal, or tax advice. Examples on this page are hypothetical and for educational purposes only.